
Lumentum is sold out into 2029 and the stock just went on sale
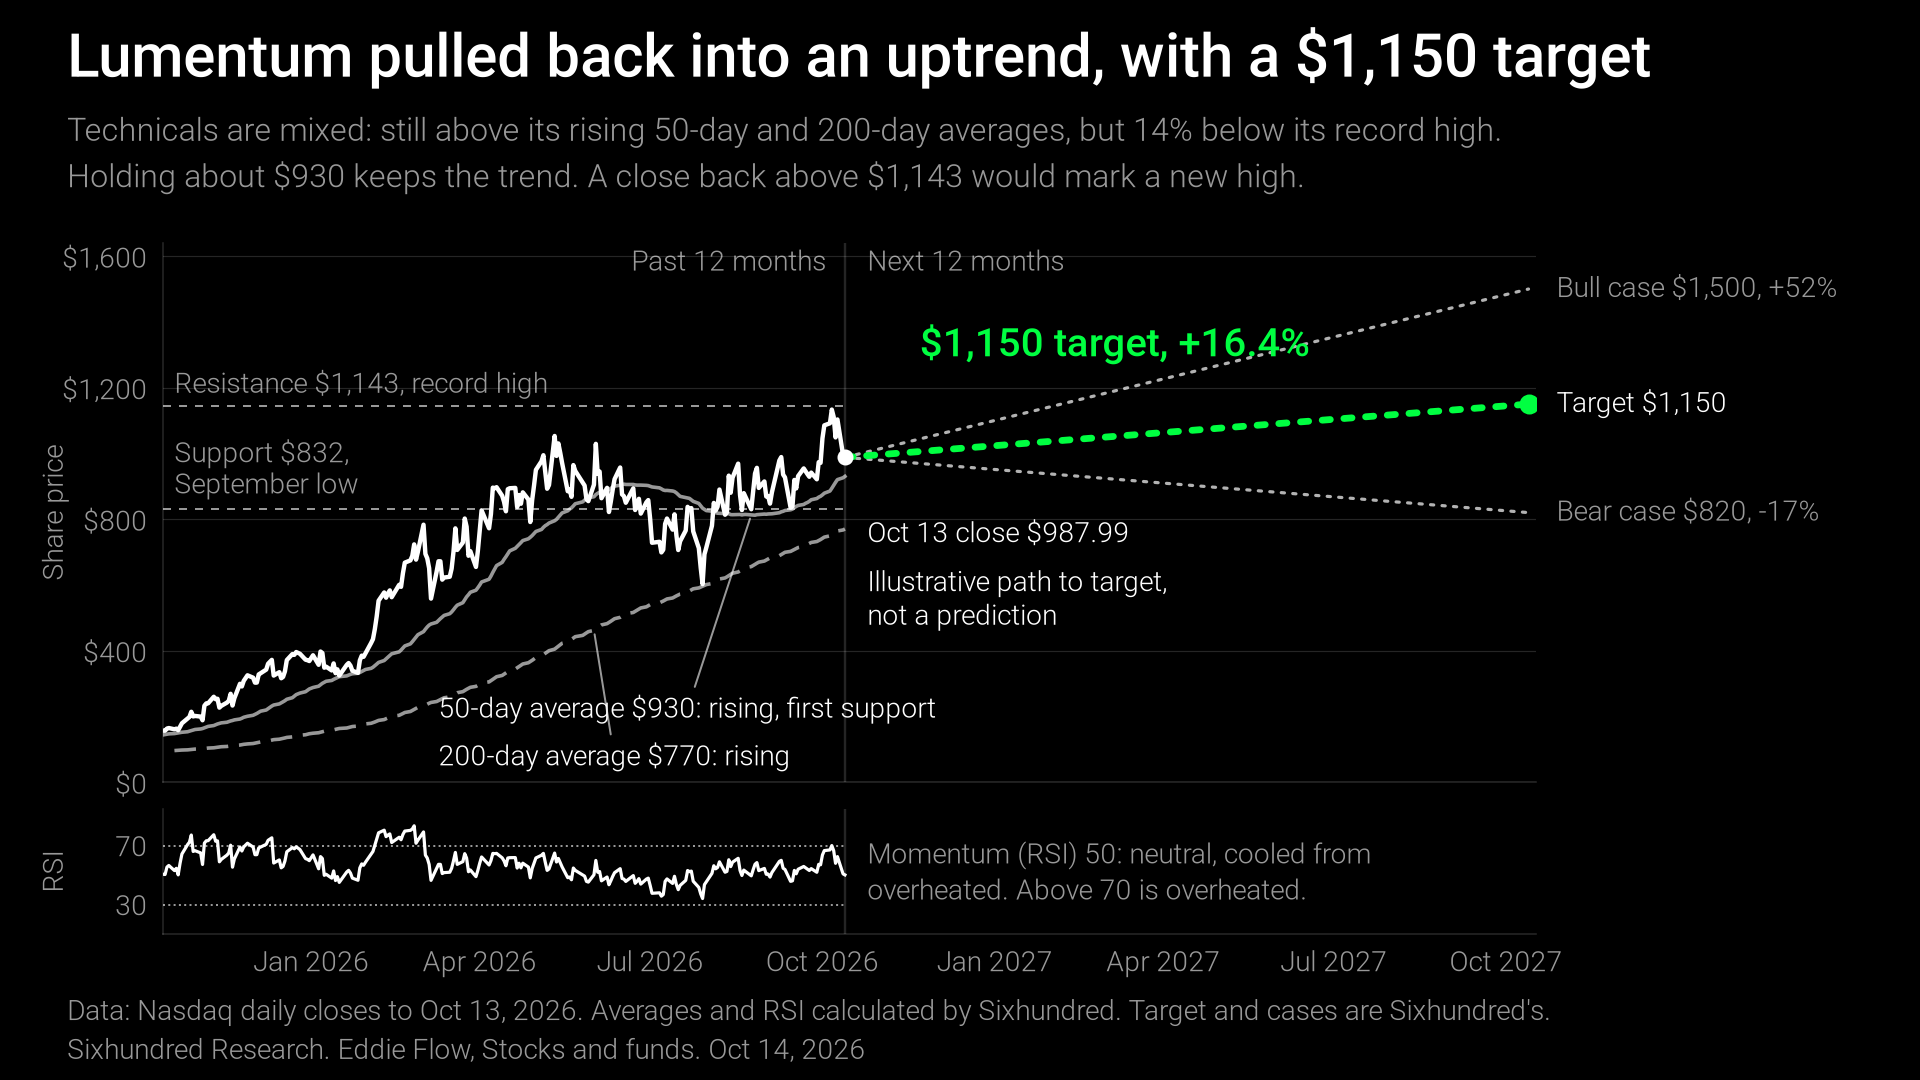
Rating: Buy. 12-month price target: $1,150, or 16.4% above the Oct 13 close of $987.99. Lumentum Holdings (LITE) makes the lasers and optical parts that move data between AI chips in data centers. On Oct 9 its chief executive said those parts are sold out into early 2029. Three days later the stock fell 9.8% with the AI sector, on no news of its own. We see a buying chance.
Key data
- Share price: $987.99, 11% below the Oct 7 close.
- Market value: about $89.5 billion.
- 52-week range: $152.54 to $1,143.00, up about 560% in a year.
Why we like it
AI data centers are switching from copper to light to link their chips, because light is faster and uses less power. Lumentum makes the laser chips inside those links.
Sales in the year to June 2026 rose 83% to $3.01 billion, and September-quarter sales should more than double.
The Oct 12 drop followed Broadcom's chief executive saying money, not chips, may limit AI building. No supplier has reported a change in orders, and analysts' profit forecasts for Lumentum have edged up since Oct 8.
Earnings and valuation
- Year to June 2026, actual: adjusted profit per share $8.67.
- Year to June 2027, estimate: $21.79.
- Year to June 2028, estimate: $36.02.
Adjusted figures leave out one-time items, chiefly a non-cash loss from swapping convertible bonds for stock.
The price-to-earnings ratio (P/E) is the share price divided by a year's expected profit per share. At the Oct 13 close, Lumentum trades at 45 times expected profit for the year to June 2027, against 34 for Ciena and 31 for Coherent on their own fiscal 2027 estimates. The premium buys faster growth: expected profit growth of 151% this fiscal year, versus 65% to 68% for the peers.
A year from now, investors will be pricing the year to June 2028. Our target is 32 times that year's expected $36.02, or about $1,153, rounded to $1,150. That is below today's multiple.
Bull, base and bear cases
- Bull, $1,500 (25% odds): supply stays tight into 2029 and prices hold.
- Base, $1,153 (50% odds): 32 times expected profit for the year to June 2028.
- Bear, $820 (25% odds): AI spending pauses and the multiple shrinks.
Catalyst
- Thu Nov 5, after the close: September-quarter results, call at 5:00 pm ET.
Risks
- At 16.4%, the upside is just over our 15% bar for a Buy.
- The stock swings hard; 10% days can recur.
- At 45 times expected profit for the year to June 2027, any slip in growth would hurt.
- If AI buyers struggle to raise money, orders could be delayed.
Disclosure
Sixhundred research is not investment advice.